Start Early, Proceed Systematically, Look Long Term

Let Your Money Work For You

Let Your Money Work For You
All You Wanted to know about money
Showing posts with label Savings. Show all posts

Saturday, May 1, 2010

After USA, it is the turn of Europe: How well did you prepare

The international events are having a toll on your savings and investments through three routes:
  • The inflation
  • The interest rates and
  • The exchange rates

The foreign entities affect your investments in the capital markets as they buy and sell securities irrespective of the asset class : equity, debt, gold, oil or other commodities or any kind of derivatives. The domestic government can shield you on one front while the other forces may combine to ruin your asset values. That means you are chasing a moving target and needs keep pace with times.

First of all, do not have the feel that it is a life time happening, it will not happen again.

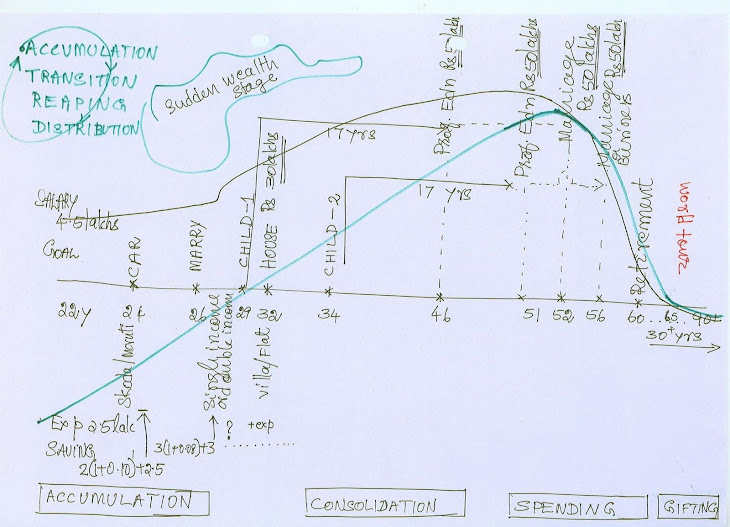
Second identify the assets, liabilities you want to fulfill in your lifetime and possible time span when you would accomplish your finnacial goals. Look at whether any point in life time your assets will pay for your needs. Many a Gap can be fixed with proper planning... and then re-look at your Financial plan.

When to look or re-look at your Financial plan?

as a student

on a first job

a job shift

first marriage

first child

first house

first vehicle

any life event...

or a shift in govt policy at home.......

or even an international event like the sub prime crisis of USA or the economic turmoils of Europe should trigger a review of your Financial plan

Companies reduce the size of IPOs, re-work their pricing anticipating a fall in capital markets key indices...

How did the Indian Equity markets welcome the news on Greece, Portugal, Spain and Germany ?

Recall the USA's subprime crisis and its after effects when the waves reached the Indian shore. In spite of JNREGP, JNRUM, wage rises to Govt employees, UGC packages to Teachers we experienced rise in prices, a freez on campus recruitments.....

the Reliance Power Ltd IPO price fixed at Rs.450.00. The markets turned sore and the prices tumbled at the bourses. and finally, a re-pricing by passing 3 for 5 bonus to look good and feel good.

It is not only equity, it affects debt too.

The interest rates goes up in the market. You hear about rising infaltion and gold prices sky rocketing. Comes with an appreciating rupee ...What about inflation? The measures taken from Budget 2009 till date and the Central Bank efforts did it tame inflation? Irrespective of the classification(Food/Non-Food/Fuel/Manufactured Products), it takes away your savings or investments unknowingly. And the Central banks across world continue trying their best to keep the three horses pulling in opposite direction in control.

Look at the way the RBI took it through. A similar situation is again on the anwil, triggered this time from Europe?

So you have to take charge of your life. Do not leave things to Government to tell you to save through the SEC 80 C under Income Tax Act 1961 or similar routes. You can surely make use of these avenues to reduce tax impacts and enhance value of your savings and investments through all legitimate purposes. Gone are the days of save, invest and forget. You have to look after your investments just like you look after your paddy field or children...

Reserve a day for looking at your investments just like you take a weekly off..

All the best.

Saturday, April 17, 2010

The ULIP War ??

The Unit Linked Insurance Plan designed to bring you best of both worlds -- the Capital Markets and Insurance has recently caught in the middle of two fighting regulators for dominnace. Which side are you?


Let us try to understand the product first:


Investor puts a certain amount of money at pre-determined intervals for a specified period of time. Thus it has characteristics of a pure SIP , the familiar Systematic Investment Plan. This is what you get from Mutual Funds. Now imagine, if you have a term insurance attached to it covering your life for all that period you run your SIP. Now what you have is a hybrid of both Capital Market and Insurance - the ULIP


Now a bit of history:


UTI brought up ULIP 1971 as their second scheme with a tie-up from LIC of India offering Insurance coverage at a limited sum assured.


When privatrisation of Insurance industry took place in year 2000, the private Insurance players found the path opened by UTI & LIC to offer varying sum assured and captured the tag 'ULIP' itself to dominate forgetting about their own primary objective to offer protection products to the people at large. Common feature being mortality charges are not linked to age in many of them as is the case with maiden ULIP from UTI way back in 1971. No assured bonus or partly assured bonus is there in them other than the market value of investments left to the credit of the insured.

In a last bid effort to save themselves from oblivion, the MFs re-vamped their schemes with higher Sum Assured and somehow tried to remain floating. UTI, DSP-BR, Reliance and Birla SL were there facing the onslaught of private insurance companies. Among them only UTI tied the mortality rate to age and kept it distinctively different from its other schemes. Others just made it a rider for open ended schemes where SIP is permitted. And SEBI made a ban of entry loads for new or existing schemes of MFs with effect from August 2009 . Added to it , very stringent disclosure norms regarding Net Asset Value, Portfolio and Deployment of the funds and finally Charges collected from investors.


In 2008, the Insurance Council of India, the self regulatory authority of Insurance companies pulled the first shot by forbidding insurance companies to co-operate with MFs to launch ULIPs/and severe all such relationships.


Sensing trouble, AMFI took up the cause of MFs and forced SEBI for an enquiry to overlapping to the capital market. It gave notice to 14 insurance companies for violating SEBI norms for dealing in Capital market products. Now in 2010, SEBI has banned fresh issue of all such products by any body in the market. IRDA followed suit. Finally, the Finance Ministry has told both regulators to abide by legal decision in the matter. More than a turf war, there is a question of governance, ethics, and morality about planting trees on the fence leading to legal battle across generations!!


When Gold ETFs were to be introduced in the market, there has been a lot of negotiations among experts, Forward Market Commission and SEBI finally decided that it shall be offered through the MF route considering the complexities of the product and need for stringency in laws and enforcement.

Similarly when REALTY was to be securitised the MF route was insisted than the Investment Trust route as in the western countries.

Going forward?

Let good sense prevail upon all so that a good product does not face extinction . Pl understand Insurance is protection and not investment. Investment is to manage risk and genertae return. Protection is to bring consolation in the event of an event happening. Both are different.

Use these products distinctively different in your financial plan, you will succeed in meeting your life needs.


Related links

1. The highest NAV Assurances?
2. Savings through Protection Plans
3. Protection Planning